Shop
SHOP-IT
COMPRE COM FACILIDADE /BUY WITH EASE
View productInternational edition
Markets · Politics · History
 Mente forte, finanças inteligentes
An independent perspective
Shop
COMPRE COM FACILIDADE /BUY WITH EASE
View product
Shop
COMPRE AQUI
View productRates are the gravity of financial markets. Learn the simple valuation math behind why stocks often fall when rates rise, and how to read a central bank cycle.
By Psycho of Finance
Published by Psycho of Finance
Every investor hears that "the Fed moves markets". Few can explain why. The mechanism is not mysterious: interest rates are the price of money and the starting point for valuing almost every asset. When that price changes, everything else reprices.
A company's value is the sum of the cash it will generate, discounted back to today. The discount rate is built from a risk-free rate, usually the government bond yield, plus a premium for the extra risk of owning stocks. When bond yields rise, the discount rate rises, and the same future cash is worth less today.
A simple version of the math: value is roughly cash flow divided by the discount rate minus the long-run growth rate.
Two points on the discount rate cut the fair multiple by more than a third. Nothing about the business changed. Only the price of money did.
Companies whose profits are expected far in the future, such as early-stage tech, are like long-duration bonds. Their value depends heavily on distant cash flows, so a higher discount rate hits them harder than it hits steady, cash-rich businesses. This is why the Nasdaq usually moves more than the Dow when rate expectations change.
When a safe government bond pays 4 or 5 percent, stocks have to offer more to attract money. Investors compare the earnings yield of the market with bond yields. As bonds become more attractive, some money rotates out of equities, which pressures prices even without any change in company results.
Higher rates raise borrowing costs for firms with debt, slow consumer spending on loans and mortgages, and can compress margins. Lower rates do the opposite. Banks, real estate, utilities, small caps and highly indebted companies are usually the most sensitive.
In 2022 the US Federal Reserve began its fastest tightening cycle in decades, lifting its policy rate from near zero to above 4 percent within the year and to more than 5 percent by mid-2023. The S&P 500 fell roughly 19 percent in 2022 and the Nasdaq Composite about a third. Bonds also fell, so the traditional 60/40 portfolio had one of its worst years in a long time. Earnings did not collapse. Valuations did.
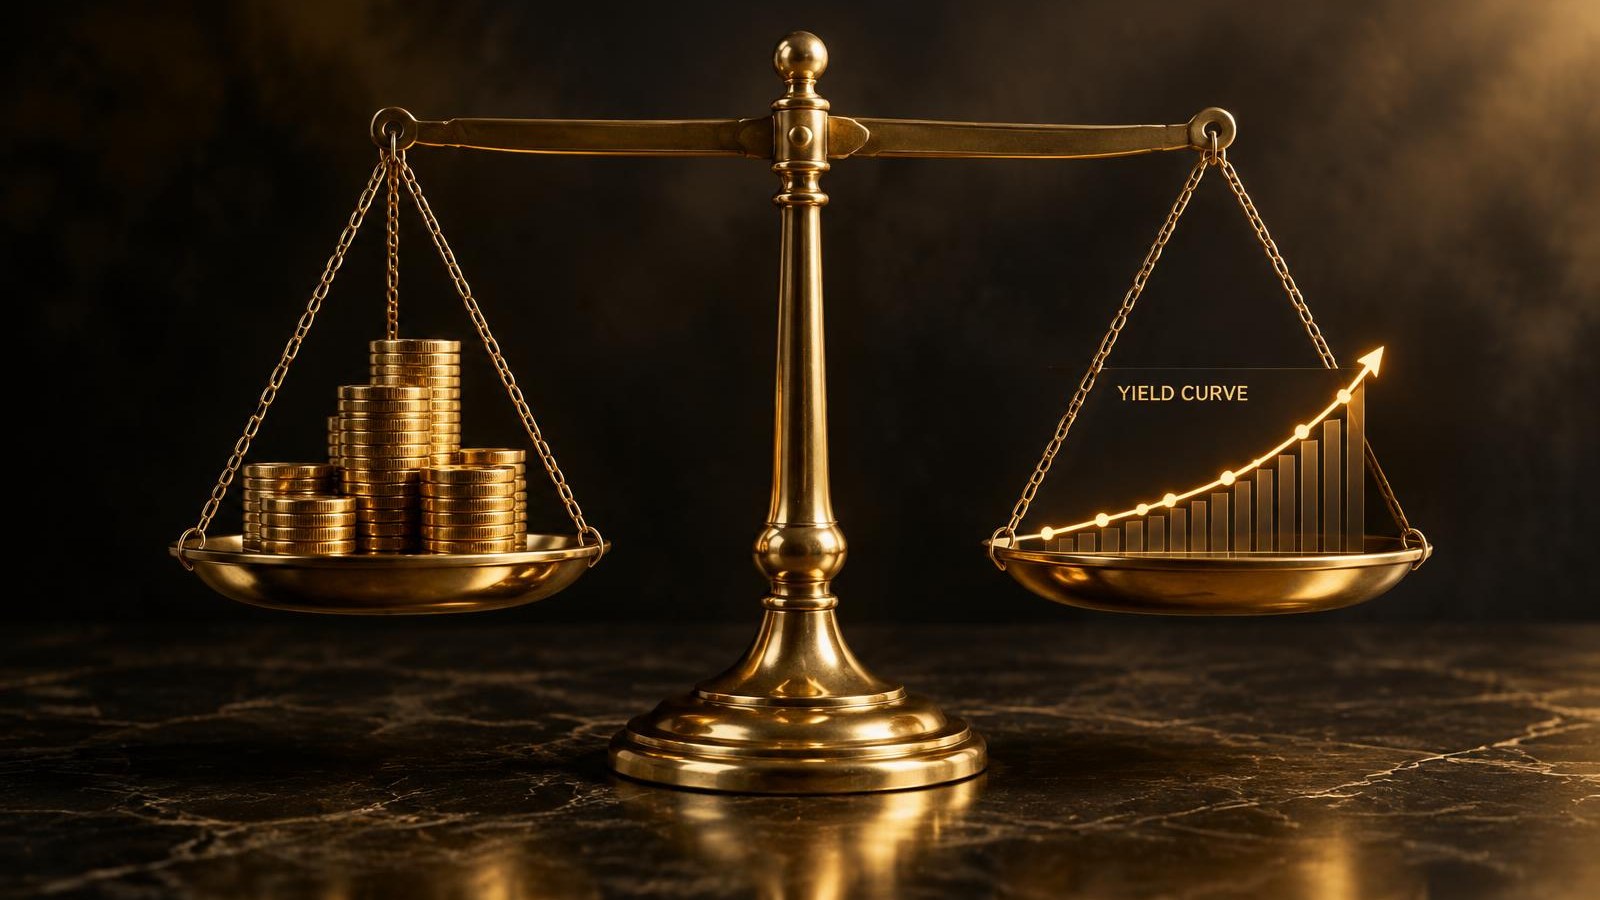
The yield curve plots government bond yields across maturities. Normally, long-term bonds yield more than short-term ones. When short-term yields rise above long-term yields, the curve is "inverted", a pattern that has preceded many US recessions, though the timing is loose and it is not a precise signal.
Interest rates sit underneath every valuation. Learn the discount-rate math, watch the long-term yield, and ask why rates are moving rather than just how much. Understanding rate cycles also explains why speculative assets, from tech stocks to crypto, tend to boom when money is cheap and struggle when it tightens, a pattern repeated across 400 years of bubbles.
This article is educational and is not financial advice.
You check your balance. $12,450.32. Rent is paid. Emergency fund is full. And yet your chest tightens. You feel broke. If this is you, you don't have a math problem. You have a brain problem. Psychologists are calling it Money Dysmorphia — and in 2026, it's an epidemic.
Equities enter April with mixed signals as rate-cut expectations collide with sticky inflation and a fragile geopolitical backdrop.
AI capex is no longer a free pass. Hyperscaler margins are now the single most-watched metric on the Street.